
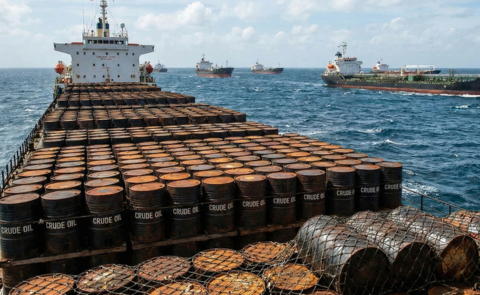
The UAE’s recent exit from OPEC on May 1, 2026, is further acknowledgement of the reality of the oil market – that in spite of the current disruption due to the U.S.-Iran war, in the long run, there will be a global surplus of oil supply. OPEC’s ability to move oil markets was at its peak in the early 2000s, when there were real fears of oil running out. Additional oil production from the U.S. shale has since made those fears, and OPEC’s ability to move the market, redundant. The UAE’s exit from the cartel is a belated recognition of the changed circumstances.
The U.S. Secretary of State Marco Rubio, during his recent visit to India, expressed a desire to sell more energy, primarily oil and natural gas, to India.[1] The U.S. is the world’s largest producer of oil: during 2025, it produced almost as much oil as Saudi Arabia and Russia – the second and third largest producers, respectively – combined. It is also the largest exporter of natural gas and seeks new markets for its resources. Export of natural gas and agricultural produce has been a major agenda item for President Donald Trump in many of his trade agreements.
For India, both are welcome developments. It is the world’s second-largest oil importer (after China) with net imports of over 4 million barrels/day, accounting for 85%-90% of total consumption. Multiple estimates project that India’s oil demand will reach or surpass 10 million barrels/day by 2050, with imports providing 90% of the consumption. India’s leaders continue to harp on energy self-sufficiency, but that is mostly rhetoric and will not meaningfully alter the numbers. A well-supplied oil market ensures that by and large, India will be able to import energy at an affordable price. The U.S. desire to sell energy can and must be used for India’s gain.
While oil prices will generally remain moderate, around $70-80, India will still have to deal with the occasional crises – such as the present one – which are a part of the oil market. One way to reduce the impact of price shocks is to invest in oil fields overseas – the higher income from these assets partly offsets the burden of higher prices. Historically, India started to invest in overseas oil fields in the early 2000s, with investments in Russia, Vietnam, Myanmar, Mozambique and Brazil, amongst others. However, these investments have slowed down, with just one investment made over the past decade.[2]
This is partly due to the Indian government’s effort on renewable energy and sustainability made over the past decade and the voluble push for electric vehicles by various arms of the government, which may have discouraged Indian oil companies from investing in oil fields. This is clearly a mistake: oil will not be replaced by renewable energy soon, and India will still need to protect itself against price spikes like the one it is facing now.
India must now again start investing in foreign oil assets, but this time focus on stable, advanced countries such as the U.S., which has the world’s largest and most liquid financial markets and also the largest number of oil companies ranging from very small to very large, like Exxon and Chevron. India should approach these purely as a financial investor – not an operator. Most Western countries have become sensitive about resource ownership by foreign governments, owing to the many Chinese acquisitions made in their markets. And accidents do happen. In case of an accident such as the Gulf of Mexico oil spill, an operator can have virtually unlimited liability. A financial investment limits India’s exposure.
Additionally, as a buyer of and an investor in the American energy sector, India may also gain a degree of political cover in the U.S. on issues such as trade and tariffs.
Another critical partner for India is the UAE. The country’s recent exit from OPEC openly declares its interest in selling more oil – the U.S. has long been frustrated that its past production was often capped by OPEC ‘quotas’. The UAE is also one of the few OPEC members with spare production capacity of over 1 million barrels/day – created at a cost of tens of billions of dollars and kept deliberately idle by OPEC in a futile attempt to manage oil prices.
As a large buyer with a growing need for oil, India will be a major market for the UAE – which the Emirate recognises. One of the outcomes of Prime Minister Modi’s recent visit to the UAE was an agreement by the latter to enhance its participation in India’s strategic petroleum reserves (SPR) and to work to establish gas reserves as well. [3]
A more ambitious and transformative collaboration between the two countries can be the creation of a new benchmark for oil, which is more reflective of the current market realities. While global oil demand has shifted from the West to Asia, prices for oil are still set on western exchanges – primarily ICE London (Brent). India’s commodity exchange MCX has an active trade in oil contracts, but it is very shallow – almost entirely close to the expiry date of contracts, and it doesn’t have physical delivery – indicating that most of this trade is paper speculation.
Being a price-setter will require actual oil sellers such as Abu Dhabi National Oil Company and Indian refiners’ buyers such as Indian Oil Corporation, Bharat Petroleum Corporation Limited, and Hindustan Petroleum Corporation Limited to carry out a part of their trade on the MCX, together with oil traders and speculators, to enable price discovery. Second, these contracts should require physical delivery of oil – preferably at one of the SPRs/oil terminals where UAE oil is being stored in India. Third, India should allow any investor/trader/oil company to hold oil in these SPRs to back buying/selling on the exchange – as long as the oil is physically present in India and available in an emergency, it serves the purpose of a strategic reserve.
Financial markets are an important component of energy security. As a large oil consumer with a free market economy, India should use its growing heft as a buyer to use the markets to its advantage.
Amit Bhandari is Senior Fellow for Energy, Investment and Connectivity.
This article was exclusively written for Gateway House: Indian Council on Global Relations. You can read more exclusive content here.
Support our work here.
For permission to republish, please contact outreach@gatewayhouse.in
©Copyright 2026 Gateway House: Indian Council on Global Relations. All rights reserved. Any unauthorised copying or reproduction is strictly prohibited.
References:
[1] U.S. Department of State. “Secretary of State Marco Rubio Remarks to Press at the Miami Homestead Airport.” https://www.state.gov/releases/office-of-the-spokesperson/secretary-of-state-marco-rubio-remarks-to-press-at-the-miami-homestead-airport
[2] ONGC Videsh Limited. “Middle East.” https://ongcvidesh.com/assets/middle-east/
[3] Ministry of External Affairs, Government of India. 2026. “Transcript of Joint Press Conference by EAM Dr. S Jaishankar and US Secretary of State Marco Rubio (May 24, 2026).” https://www.mea.gov.in/media-briefings.htm?dtl/41227/Transcript+of+Joint+Press+conference+by+EAM+Dr+S+Jaishankar+and+