
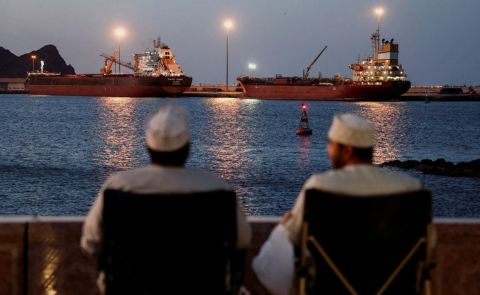
The renewal of hostilities between the U.S. and Iran has created fresh uncertainty around energy prices. It raises three key questions. First, regarding the outlook for global oil markets: can prices go up further? Second, will there be new sanctions-related risks for oil buyers? Third, what strategies can oil importers use to manage their risks? Each of these questions is especially relevant for India, which consumes over 4.5 million barrels/day of oil and relies on imports for over 85% of its growing needs. Over the next two decades, India’s oil consumption is projected to double, reaching 10 million barrels/day.
The price of oil has been in the $85-95/barrel range since the conflict restarted in early July – an increase of 20% over the $70-72/barrel range in late June when the ceasefire was in place. At the peak of the conflict in March and April, the maximum price was $120/barrel – the single biggest disruption to global oil supply since World War II.
This is a sharp contrast from the 2005-07 era, when oil supply was tight, and news such as an accident in an oil field or a terror attack in an oil-producing country was enough to send the price soaring. At that time, oil had crossed $140/barrel, well over the $200/barrel in today’s money. Judging by the relatively sluggish movements in oil prices of the past six months compared to the magnitude of such moves historically, it can be concluded that the global oil supply worldwide comfortably exceeds the demand.
Historically, OPEC has been regarded as the swing producer in the oil market, which sets prices by reducing or increasing oil production. However, it has lost this position over the past several years, largely due to rising oil production in the U.S. and falling oil demand from the Western world due to green policies.
Today, the shale oil producers in the U.S. are the true swing producers. The UAE’s exit from OPEC is a belated acknowledgement that the grouping is no longer a swing producer, and keeping ‘spare production capacity’, which Saudi Arabia and the UAE have traditionally maintained, incurs a cost without commensurate benefits. Once the situation in the Persian Gulf normalises, the UAE is likely to increase its production – and India will be a beneficiary.
Supply can be managed. But a new risk from the conflict is the use of sanctions and other related financial measures by the U.S., which has been unable to achieve its original aims on Russia and Iran via kinetic means. The Supporting Russia Act of 2026 proposes tariffs of up to 100% on countries importing Russian oil is an example. While most non-Western governments don’t recognise unilateral or American sanctions, multinational corporations have to contend with the reality of American centrality to the global financial system and plan and act accordingly. An oil company requires continued access to international financial markets to remain a going concern. Russia and Iran are two of the most heavily sanctioned countries and will continue to be at the receiving end of the U.S. exercising its leverage periodically. Given the surplus oil capacity in the world market, the U.S. will have greater freedom of action on this front, while exporters will be more vulnerable.
As an oil importer, these are risks that India will need to manage. Historically, India has invested in overseas oil and gas fields since the early 2000s to reduce the financial exposure to high oil prices. Over the past decade, outbound acquisitions by Indian oil companies have virtually come to a halt. This could have been due to the public signalling by the Indian government on renewable energy and green technologies but also because managing those oil fields at a long distance has been difficult.
Since 2019, Indian policymakers have pushed aggressively for electric vehicles, including support for manufacturing and other subsidies. However, penetration remains low at less than 5% for cars and 10% for two-wheelers. This is perhaps the lowest penetration of EVs for any major automotive market. Unless the issues related to the supply of critical minerals, including rare earth magnets, and China’s dominance of the supply chain are addressed, adoption will lag.
The other way in which India is trying to deal with high oil prices is by aggressively pushing for biofuels – ethanol, which can be blended with petrol. This is a faulty strategy, as it diverts agricultural land to growing cheap fuel. The ‘savings’ from importing less oil are illusory, as India ends up importing more oilseeds and pulses – crops which have been supplanted by bio-fuels. Crops used for ethanol production – sugarcane and maize – are also water-intensive, and India remains the most water-stressed among major economies.
India needs to re-examine its reluctance to invest in overseas oil and gas fields. Given the backdrop of sanctions, some of these investments can be based in jurisdictions less likely to be hit by sanctions – resource rich states such as the U.S., Canada, and Australia. The low energy prices of the past decade have been helpful tailwind for India, and the events of the past few months show why long-term preparation beats crisis management.
Amit Bhandari is Senior Fellow for Energy, Investment and Connectivity.
This article was exclusively written for Gateway House: Indian Council on Global Relations. You can read more exclusive content here.
Support our work here.
For permission to republish, please contact outreach@gatewayhouse.in
© Copyright 2026 Gateway House: Indian Council on Global Relations. All rights reserved. Any unauthorised copying or reproduction is strictly prohibited.